Serving Toronto, Mississauga & the Greater Toronto Area — remote across Ontario
Nova Ledgers insights
E-commerce Bookkeeping: Top Tips for Online Sellers
A practical guide to organizing sales, fees, inventory, taxes, and financial records for Canadian e-commerce businesses.
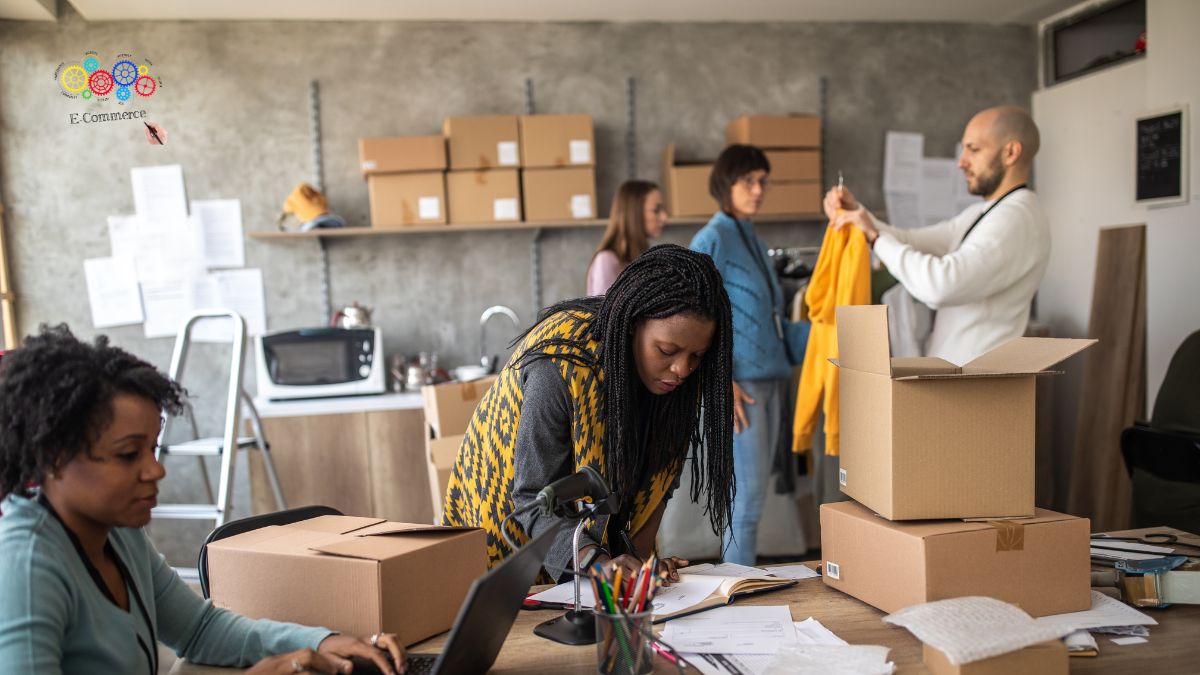
E-commerce businesses move quickly. Orders arrive from multiple channels, payments flow through different platforms, inventory levels change constantly, and returns or chargebacks can appear without warning. In that environment, bookkeeping is often pushed to the bottom of the priority list.
But accurate financial records are essential for understanding profitability, managing cash flow, planning inventory purchases, and preparing for tax time. A clear bookkeeping process helps you make decisions based on current information rather than guessing from your bank balance.
Why e-commerce bookkeeping is different
Online selling creates bookkeeping challenges that many traditional businesses do not face. You may sell through your own website and multiple marketplaces, collect payments through third-party processors, pay platform fees and advertising costs, manage inventory across locations or fulfillment services, and deal with returns, refunds, and chargebacks.
These moving parts make it important to build a system that can handle high transaction volume, multiple sales channels, and complex fee structures without becoming overwhelming.
1
Integrate sales channels with your accounting system
Many e-commerce sellers operate across several platforms: an online store, one or more marketplaces, social-commerce channels, and possibly in-person or wholesale sales. Each channel generates orders, fees, payouts, and sometimes returns or adjustments.
Integrating your sales channels with accounting software can reduce manual data entry and help ensure that revenue, fees, and payouts are recorded consistently. This is especially useful when payouts to your bank account do not match the gross sales amount because of platform fees, chargebacks, or other deductions.
Practical step: Map each sales channel and payment processor to specific
income and fee accounts. Review a sample of transactions to confirm that gross sales,
fees, and net payouts are recorded as you expect.
2
Track inventory and cost of goods sold clearly
For product-based businesses, inventory is often the largest asset and a major driver of cash flow. Knowing what you have on hand, what has been sold, and what your cost of goods sold (COGS) looks like is essential for understanding true profitability.
Inventory tracking can be done inside your accounting software, a dedicated inventory system, or an e-commerce platform that integrates with your books. The key is to keep records consistent and to reconcile inventory activity with your financial statements.
Practical step: Record purchases, adjustments, and cost of goods sold
consistently. Review inventory reports regularly and investigate large or unexpected
variances between physical counts and recorded balances.
3
Reconcile payment gateways and bank accounts regularly
Payment processors such as PayPal, Stripe, Square, or marketplace payment systems often batch transactions and deposit net amounts into your bank account after deducting fees, refunds, chargebacks, or reserves.
Reconciliation compares your internal records with statements from your bank and payment processors to identify missing, duplicate, or incorrectly recorded transactions. Doing this regularly helps catch errors early and keeps your books reliable.
Practical step: Reconcile each payment gateway and bank account monthly.
Investigate differences between recorded sales and actual deposits, and document any
adjustments or write-offs.
4
Separate business and personal finances
Mixing personal and business transactions makes bookkeeping harder and increases the risk of errors. A dedicated business bank account and credit card help you track income, expenses, and cash flow more clearly.
This separation also makes it easier to prepare financial statements, respond to funding or grant requests, and work with a tax professional.
Practical step: Route all business income and expenses through business
accounts. If you occasionally pay a business cost personally, record it clearly rather
than mixing it with ordinary business activity.
5
Understand GST/HST and other sales-tax obligations
Canadian e-commerce sellers may have obligations under the GST/HST system, provincial sales tax regimes, or marketplace-facilitator rules. Registration may be required once you exceed the CRA small-supplier threshold, which is generally $30,000 in taxable supplies, subject to the CRA’s specific rules and timing requirements. Some sellers may choose to register voluntarily in certain situations.
If you sell to customers in other provinces or internationally, additional rules may apply. Marketplace operators may collect and remit certain taxes on your behalf in some cases, but you remain responsible for understanding your own obligations.
Practical step: Track taxable sales by jurisdiction, keep sales-tax
records separate, and confirm with a qualified professional when registration or
collection is required. Review CRA guidance and provincial rules regularly as requirements
can change. [294][296][297]
6
Monitor receivables, payables, and cash flow
Cash flow is critical for e-commerce businesses. You may need to purchase inventory in advance, pay for advertising, cover platform fees, and manage returns or refunds while waiting for payouts to clear.
Tracking accounts receivable (money owed to you) and accounts payable (money you owe to suppliers, vendors, or service providers) helps you anticipate cash needs and avoid surprises.
Practical step: Review outstanding customer balances, upcoming bills,
and scheduled payouts weekly. Use this information to plan inventory purchases, marketing
spend, and other cash commitments.
7
Use automation and cloud-based tools
E-commerce businesses benefit greatly from automation. Cloud-based accounting software, integrations with sales channels and payment processors, receipt-capture tools, and inventory systems can reduce manual work and improve accuracy.
Automation does not replace judgment. It frees up time so you can focus on reviewing reports, investigating variances, and making strategic decisions rather than entering transactions by hand.
Practical step: Identify repetitive tasks such as importing sales,
categorizing expenses, generating invoices, or preparing reports. Choose tools that
automate those tasks while still allowing you to review and approve activity.
8
Review financial reports and key metrics
Financial reports provide a clearer picture of how your e-commerce business is performing. A Profit and Loss statement shows revenue, costs, and expenses. A Balance Sheet shows assets, liabilities, and equity. A cash flow report shows how money is moving in and out of the business.
In addition to standard reports, track metrics that matter to your model: gross profit margin by product or category, average order value, customer acquisition cost, return rates, and inventory turnover.
Practical step: Review financial statements monthly and compare results
to prior periods and budgets. Use the insights to adjust pricing, marketing, inventory
purchases, or operational processes.
Common e-commerce transactions to organize
E-commerce bookkeeping involves more than recording sales. The following types of transactions are common and should be tracked consistently.
Sales and fees
Gross sales, platform fees, payment-processor fees, shipping revenue, discounts, coupons, and promotional credits.
Returns and chargebacks
Refunds, returns, chargebacks, reversals, and related fee adjustments that affect net revenue and cash flow.
Inventory activity
Purchases, adjustments, write-offs, shrinkage, and cost of goods sold for products sold during the period.
Taxes and remittances
GST/HST or other sales tax collected, eligible input tax credits where applicable, and remittances to tax authorities.
Recordkeeping reminder: The CRA generally expects businesses to keep complete,
reliable books and records, including supporting documents, for six years from the end of the
last tax year they relate to. This applies to e-commerce businesses as well as other types of
enterprises. [246][248][249]
A simple monthly e-commerce bookkeeping routine
Use this checklist to stay organized
- Import or record sales, fees, refunds, and chargebacks from all channels
- Reconcile payment gateways, bank accounts, and credit cards
- Update inventory records and review cost of goods sold
- Categorize expenses and save supporting receipts and invoices
- Review GST/HST or other sales-tax collected and payable
- Check accounts receivable, accounts payable, and cash position
- Review Profit and Loss, Balance Sheet, and key performance metrics
The bottom line
E-commerce bookkeeping does not need to be overwhelming. With the right system, you can turn a high volume of transactions into organized records that support better decisions about pricing, inventory, marketing, and growth.
Start with one improvement this week: connect a sales channel to your accounting software, reconcile a payment gateway, organize your last month of expenses, or review your inventory reports. Small steps taken consistently create a stronger financial foundation over time.
Need help organizing your e-commerce books?
Nova Ledgers provides practical bookkeeping support to help online sellers create more consistent records, clearer reports, and manageable financial workflows.
Request a ConsultationDisclaimer: This article provides general educational information only and is not tax, legal, financial, or accounting advice. GST/HST, sales-tax, customs, import, and reporting obligations depend on your business structure, activities, and locations. Consult the CRA and qualified professionals for advice specific to your e-commerce business.